A share gives you a smaller entry into a larger hospitality property. The important question is not just how many square feet you buy. It is which accommodation your share belongs to, what portion of its rental income you receive, and how that income is calculated.
At Falettis Grand Hotel Ayubia, this comparison brings together a 200 sq ft Sky Villa share and three Presidential Suite options: quarter-key, half-key and full-key. We explain the ownership fractions, model the rental income and separate operating income from the three-year rental-guarantee option.
Start with the accommodation, then choose your share
Explore our guide to Falettis rooms, Presidential Suites and Sky Villas to compare the accommodation behind each ownership option.
The three-bedroom Sky Villa accommodates approximately 6–8 guests, while the Presidential Suite accommodates approximately 2–4. These capacities refer to the complete accommodation, not to each individual share.
| Option | Allocated area in this example | Interest used for rental calculations | Complete accommodation |
|---|---|---|---|
| Sky Villa share | 200 sq ft | 1/8, or 12.5% | Three-bedroom Sky Villa; approximately 6–8 guests |
| Presidential quarter-key | Approximately 180 sq ft | 1/4, or 25% | Presidential Suite; approximately 2–4 guests |
| Presidential half-key | Approximately 360 sq ft | 1/2, or 50% | Presidential Suite; approximately 2–4 guests |
| Presidential full-key | 722 sq ft | 100% | Presidential Suite; approximately 2–4 guests |
The Sky Villa example has eight equal shares. Quarter-key and half-key are fractional interests in the Presidential Suite, not separate miniature suites. Their rounded area labels do not replace the precise allocation and income rights recorded in the selected agreement. Personal stays and booking rights also follow that agreement.
How rental income is calculated
A guest’s room bill and an investor’s rental income are different amounts. Our Falettis rental-income guide explains the same calculation using a separate set of planning assumptions. For this illustration, operating expenses are deducted first, then the remaining net rental profit is shared:
1. Multiply the average nightly rate by the booked nights to calculate gross accommodation revenue.
2. Allow approximately 40% of revenue for operating costs.
3. Split the remaining rental profit: 70% to investors and 30% to management.
4. Allocate the investor portion according to the ownership fraction.
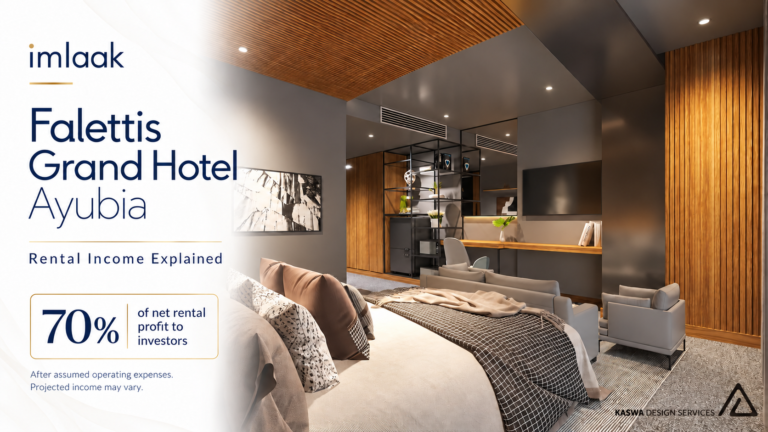
Investors receive 70% of the net rental profit remaining after the assumed 40% operating expenses are deducted. Actual costs, income allocations and owner-level taxes or charges follow the operating agreement.
Deduct expenses. Then share net profit.
1. Deduct operating expenses from gross revenue
2. Split the net profit, not the gross revenue
Investors30% of net profit
Management
For every PKR 100 of gross revenue, deduct PKR 40 in assumed expenses. Of the PKR 60 net profit remaining, investors receive 70%, or PKR 42, and management receives 30%, or PKR 18.
The nightly rates and occupancy behind the example
| Planning assumption | Complete Sky Villa | Complete Presidential Suite |
|---|---|---|
| Average nightly rate | PKR 200,000* | PKR 70,000 |
| Assumed occupancy | 50% | 60% |
| Equivalent occupied nights over 365 days | 182.5 | 219 |
| Illustrative annual gross revenue | PKR 36,500,000 | PKR 15,330,000 |
| Assumed operating costs, 40% | PKR 14,600,000 | PKR 6,132,000 |
| Rental profit after assumed costs | PKR 21,900,000 | PKR 9,198,000 |
| Investor allocation, 70% of that profit | PKR 15,330,000 | PKR 6,438,600 |
These are planning scenarios, not achieved booking results or assured rental payments. The nightly rate should represent an average across busy and quieter periods, rather than the highest holiday tariff.
*The Sky Villa rate is an approximate planning assumption of PKR 2 lakh per night, not a confirmed tariff or guaranteed booking rate.
What could each share receive?
The whole villa’s investor allocation is divided by eight. The Presidential Suite’s investor allocation is divided by four for a quarter-key, by two for a half-key, or retained in full for a full-key.
| Ownership option | Annual gross revenue attributable to interest | Illustrative annual investor allocation | Monthly average of annual investor allocation |
|---|---|---|---|
| Sky Villa: one 200 sq ft share* | PKR 4,562,500 | PKR 1,916,250 | PKR 159,688 |
| Presidential quarter-key | PKR 3,832,500 | PKR 1,609,650 | PKR 134,138 |
| Presidential half-key | PKR 7,665,000 | PKR 3,219,300 | PKR 268,275 |
| Presidential full-key | PKR 15,330,000 | PKR 6,438,600 | PKR 536,550 |
Monthly figures are rounded annual averages, not a promise of equal monthly payments. Annual figures use 365 days. Owner-level taxes and any charges outside the assumed expense allowance are not deducted here.
Different interests. A clear comparison.
After 40% expense allowance and 70% investor allocation. These are rental amounts, not ROI. *Sky Villa uses an approximate PKR 200,000/night planning assumption.
Follow one quarter-key through the calculation
At PKR 70,000 a night and 60% occupancy, the complete Presidential Suite generates an illustrative PKR 15,330,000 annually. After the assumed operating costs, PKR 9,198,000 remains. The investors’ 70% allocation is PKR 6,438,600. A quarter-key receives one quarter: PKR 1,609,650 annually, equivalent to approximately PKR 1.34 lakh a month.
The same sequence applies to a half-key and a full-key. Buying a larger interest increases the proportional income in this model; it does not change the underlying unit’s occupancy or profitability.
The alternative: 12% annual rental guarantee for three years
An eligible upfront-purchase plan offers 12% per annum for three years, subject to written terms. Buyers can compare this contractual rental option with the operating-income model above. Our Tower B payment-plan comparison shows a separate, allocation-specific example of installments and upfront alternatives. Not every allocation necessarily qualifies. The guarantee must be documented for the selected allocation, including the responsible payer, qualifying purchase amount, commencement date, payment schedule, deductions and conditions.
For illustration, if the qualifying contractual amount is PKR 1,000,000:
| Calculation | Amount |
|---|---|
| Annual rental at 12% | PKR 120,000 |
| Monthly equivalent, for comparison only | PKR 10,000 |
| Three-year rental total, without compounding | PKR 360,000 |
“Upfront purchase” means the buyer pays the purchase price upfront. It does not, by itself, mean all three years’ rent is paid immediately. The actual rental-payment schedule must be stated in the agreement.
The guarantee is a separate contractual arrangement, not an additional 12% to automatically add to the projected operating income. Purchase discounts and other plan benefits must also be compared separately unless the selected agreement explicitly combines them.
Which income approach fits your objective?
| Comparison | Operating-income illustration | Contractual rental-guarantee option |
|---|---|---|
| Calculation basis | Guest revenue, less costs, then agreed profit allocation | Agreed percentage of the qualifying contractual amount |
| Key drivers | Nightly rates, occupied nights, costs and ownership fraction | Eligibility, payer performance and written terms |
| Income pattern | Can vary with operations | Follows the agreed rental schedule |
| Term | Follows the operating arrangement | Fixed three-year term under the eligible plan |
| What to compare | Expected investor income against total purchase cost | Contracted rental against qualifying price and conditions |
The larger rupee figure is not automatically the better investment. To compare rental yield, divide annual investor income by the total acquisition cost. Without a current quotation for each interest, the table compares rental amounts, not percentage investment returns.
Two potential sources of return, one clear calculation
A smaller ownership interest can open the door to hospitality income without buying the whole accommodation. Rental cash flow is one part of the opportunity; a future increase in resale value is another. Neither should be confused with a guaranteed outcome.
Annual rental yield = annual investor income ÷ total acquisition cost × 100.
To illustrate the arithmetic only, an investment with an all-in cost of PKR 10 million would need PKR 1.5 million of annual investor income for a 15% rental yield, or PKR 2 million for a 20% yield. These are examples, not current Falettis quotations or promised returns.
| Illustrative all-in cost | Annual investor income | Rental yield |
|---|---|---|
| PKR 10,000,000 | PKR 1,000,000 | 10% |
| PKR 10,000,000 | PKR 1,500,000 | 15% |
| PKR 10,000,000 | PKR 2,000,000 | 20% |
Capital appreciation is the change in resale value, not rental income. A gain is only realised on sale and must be assessed after transaction costs and taxes. Values can fall, and a buyer may take time to find. No capital-growth rate is assumed here.
What if occupancy is lower?
At 50% rather than 60% occupancy, keeping the PKR 70,000 suite rate and the same expense model, a Presidential quarter-key’s illustrative annual income falls to PKR 1,341,375 from PKR 1,609,650. Actual expenses may not decline proportionately with bookings.
Frequently asked questions
Does a 200 sq ft share receive the whole villa’s rent?
No. In this eight-share example, it receives one eighth of the investor allocation after the modelled operating costs and management split.
Does owning a quarter-key mean I can occupy a separate 180 sq ft room?
Not necessarily. It is a fractional interest in the identified accommodation. Ownership, personal-use and reservation rights are established by the selected documents.
Are the nightly rates guaranteed?
No. They are assumptions used to illustrate the rental model. Real bookings depend on demand, seasonality, achieved prices and the property’s operation.
Can I combine the 12% guarantee with operating rent?
Only where the signed terms expressly provide for both. Do not count the same income twice.
Choose your allocation with the full picture
Start with your budget, then compare the exact allocation, purchase price, rental structure and personal-use rights. Whether you prefer a smaller Sky Villa share or a quarter, half or full Presidential key, Imlaak’s Falettis investment and management support can help you put the figures alongside the selected payment plan so you can make a clear, like-for-like comparison.
Explore our rental-income methodology or compare Falettis Tower B payment plans.